Study in Pictures🌐 English (United Kingdom)
Bookkeeping Illustrated

Digital book in PDF · read it on your phone or print it

Bookkeeping Illustrated

The T account, DEAD CLIC (which side every entry goes), day books, ledgers, the trial balance, VAT, bank reconciliation, accruals and year end. One topic on each page: the drawing first, then what you need to remember.

  • 69 illustrated pages
  • English
  • 30-day guarantee
£19.99£57.99
Get the book · £19.99

Price shown for: United Kingdom. In other countries, the checkout shows the price that applies there.

About this book

What it is

The T account, DEAD CLIC (which side every entry goes), day books, ledgers, the trial balance, VAT, bank reconciliation, accruals and year end. One topic on each page: the drawing first, then what you need to remember.

Who This Book Is For
  • You're studying AAT or ICB
  • Your exam is coming up
  • You already keep the books
What it covers
  1. The Big Picture
  2. Debit and Credit Without Memorising
  3. Books of Prime Entry
  4. Ledgers and the Trial Balance
  5. VAT and Making Tax Digital
  6. The Bank and Payroll Basics
  7. Year-End Adjustments
  8. Final Accounts
  9. Revision and Checklists
Language
English (United Kingdom)
Pages
69
Format
Digital book in PDF · read it on your phone or print it
Price
£19.99 (United Kingdom)
Delivery
This is a digital PDF book sent to your email: nothing is printed or shipped.
30-Day Guarantee
30-day guarantee: if a file doesn't open, if the content isn't what the product page describes, if you were charged twice or the email never arrived, write to us and we'll refund you in full.

Look Inside the Book

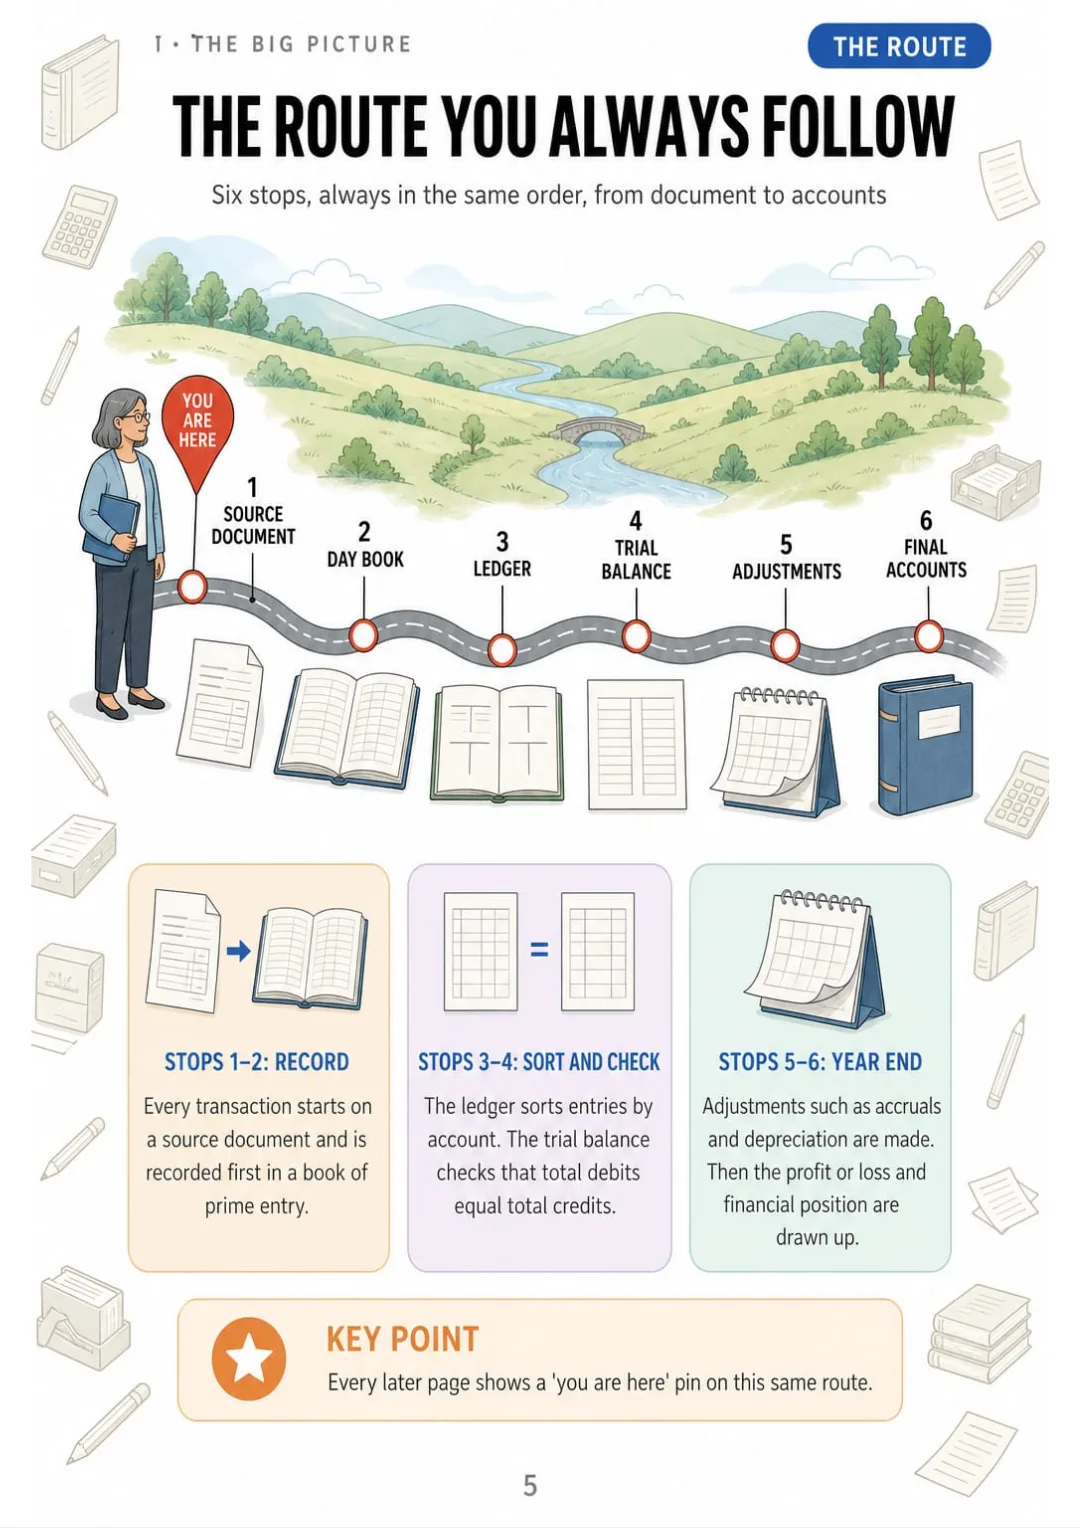
Source document → day book → ledger → trial balance → adjustments → final accounts, drawn as one map.
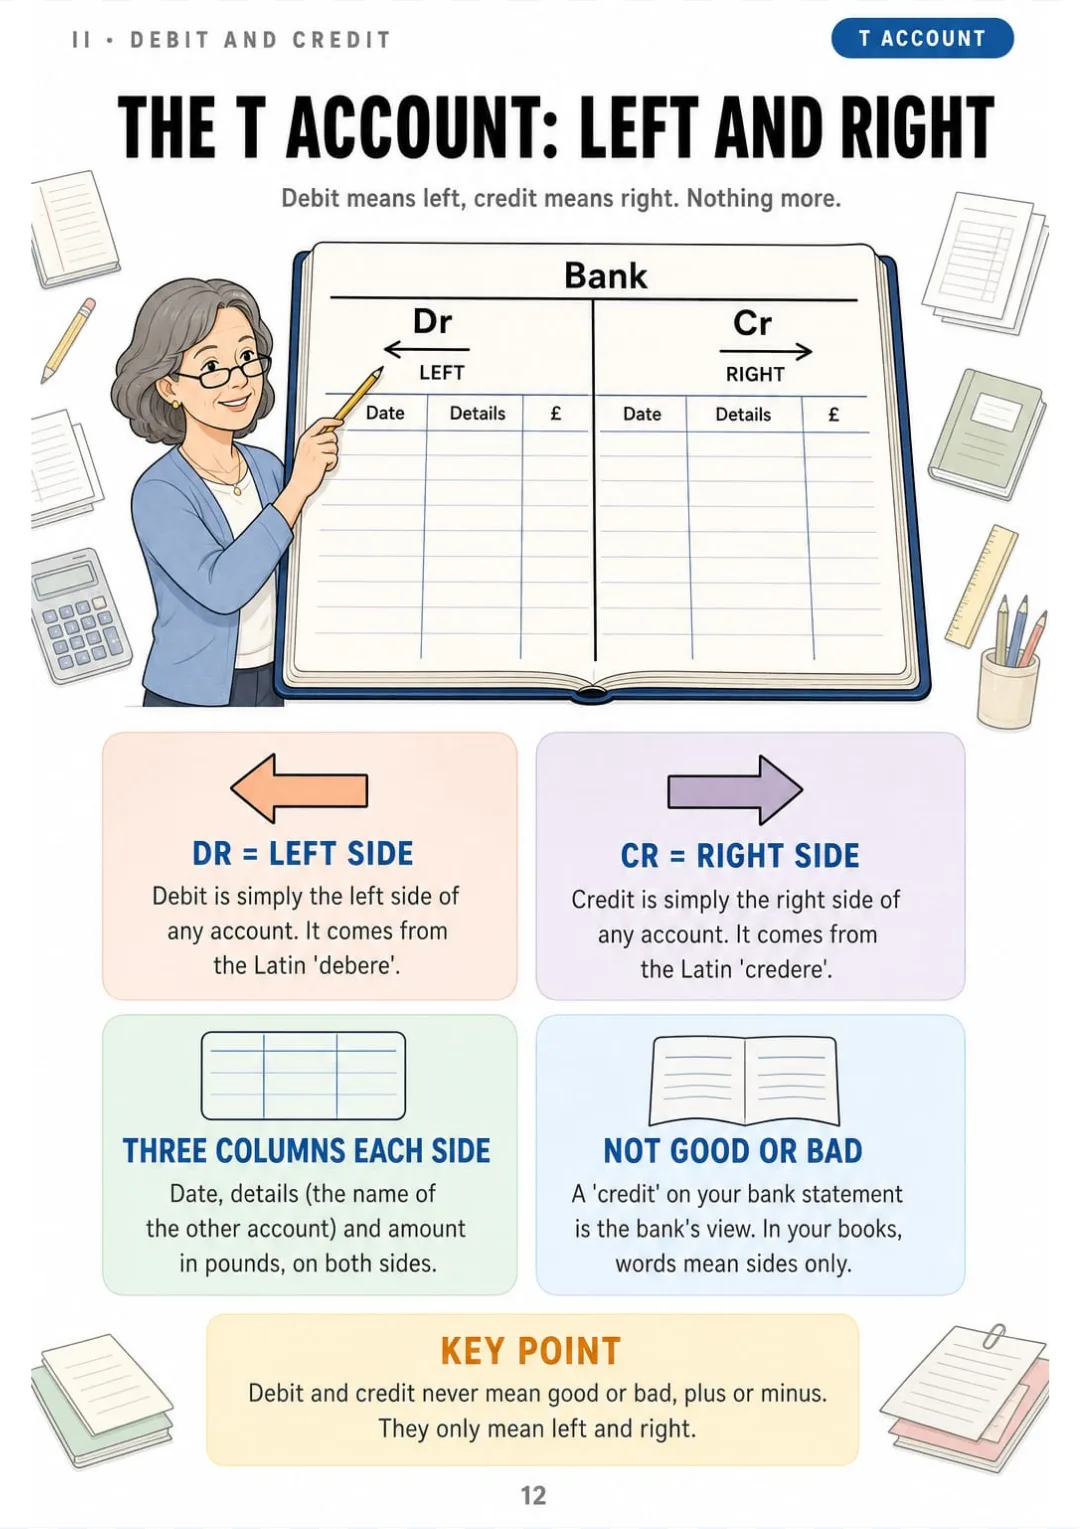
Every account is a T: Dr on the left, Cr on the right, date, details and £ on each side.
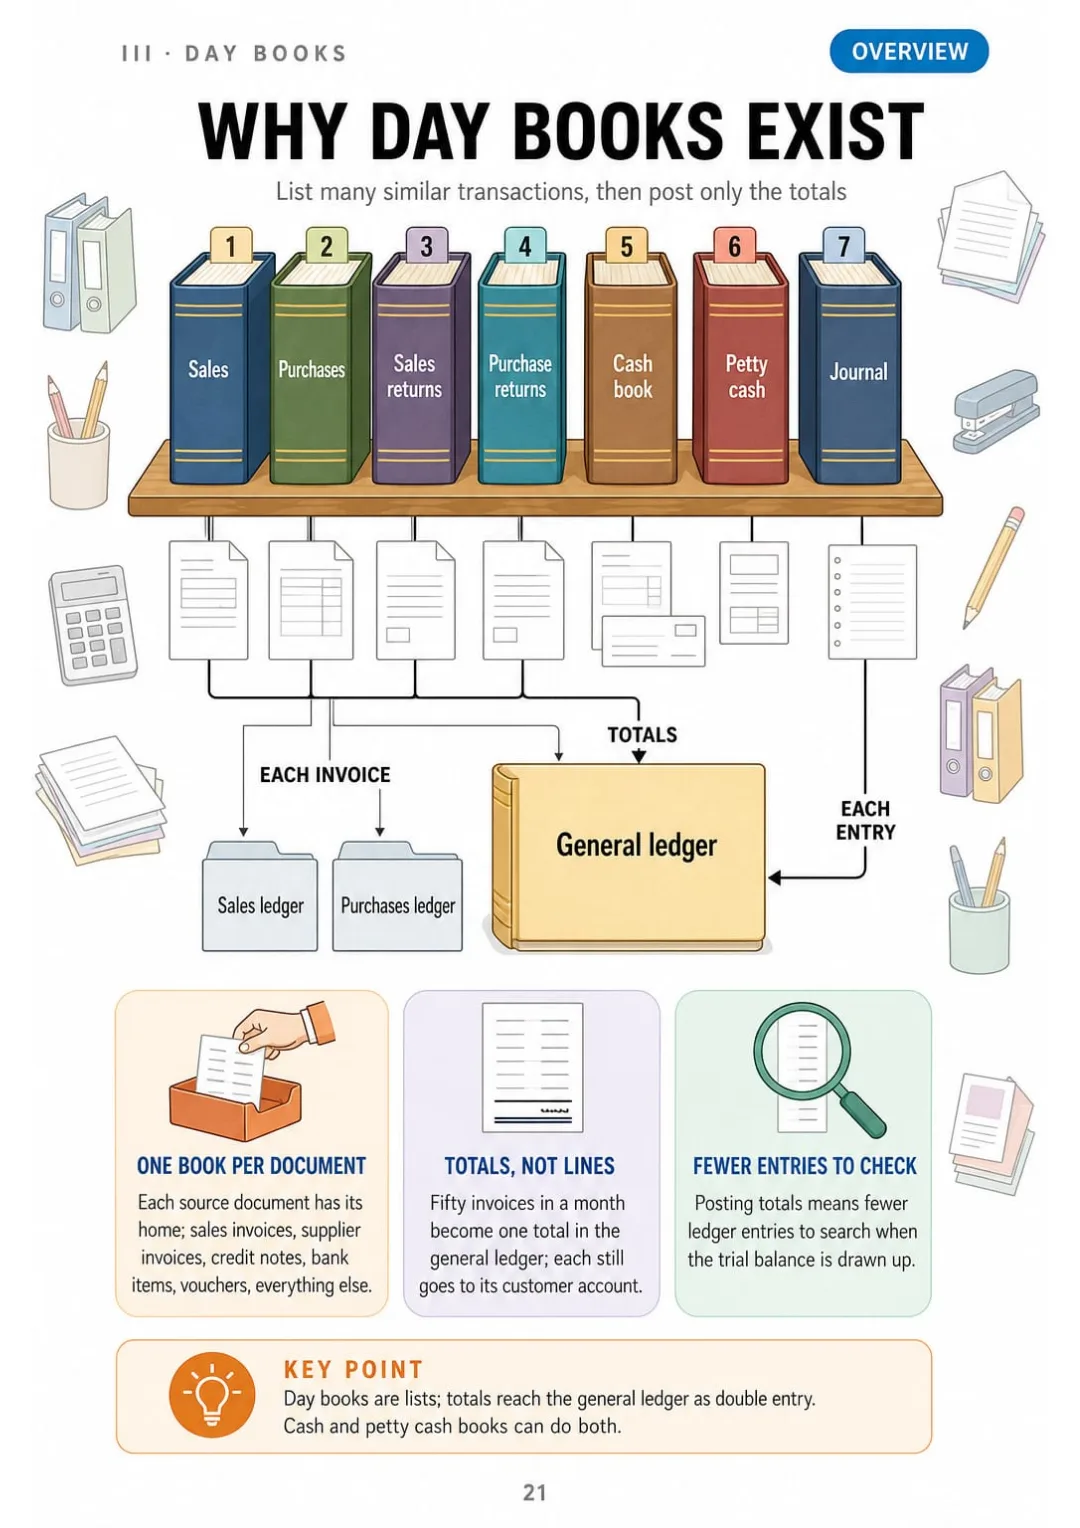
The seven books of prime entry on one shelf, each with its source document
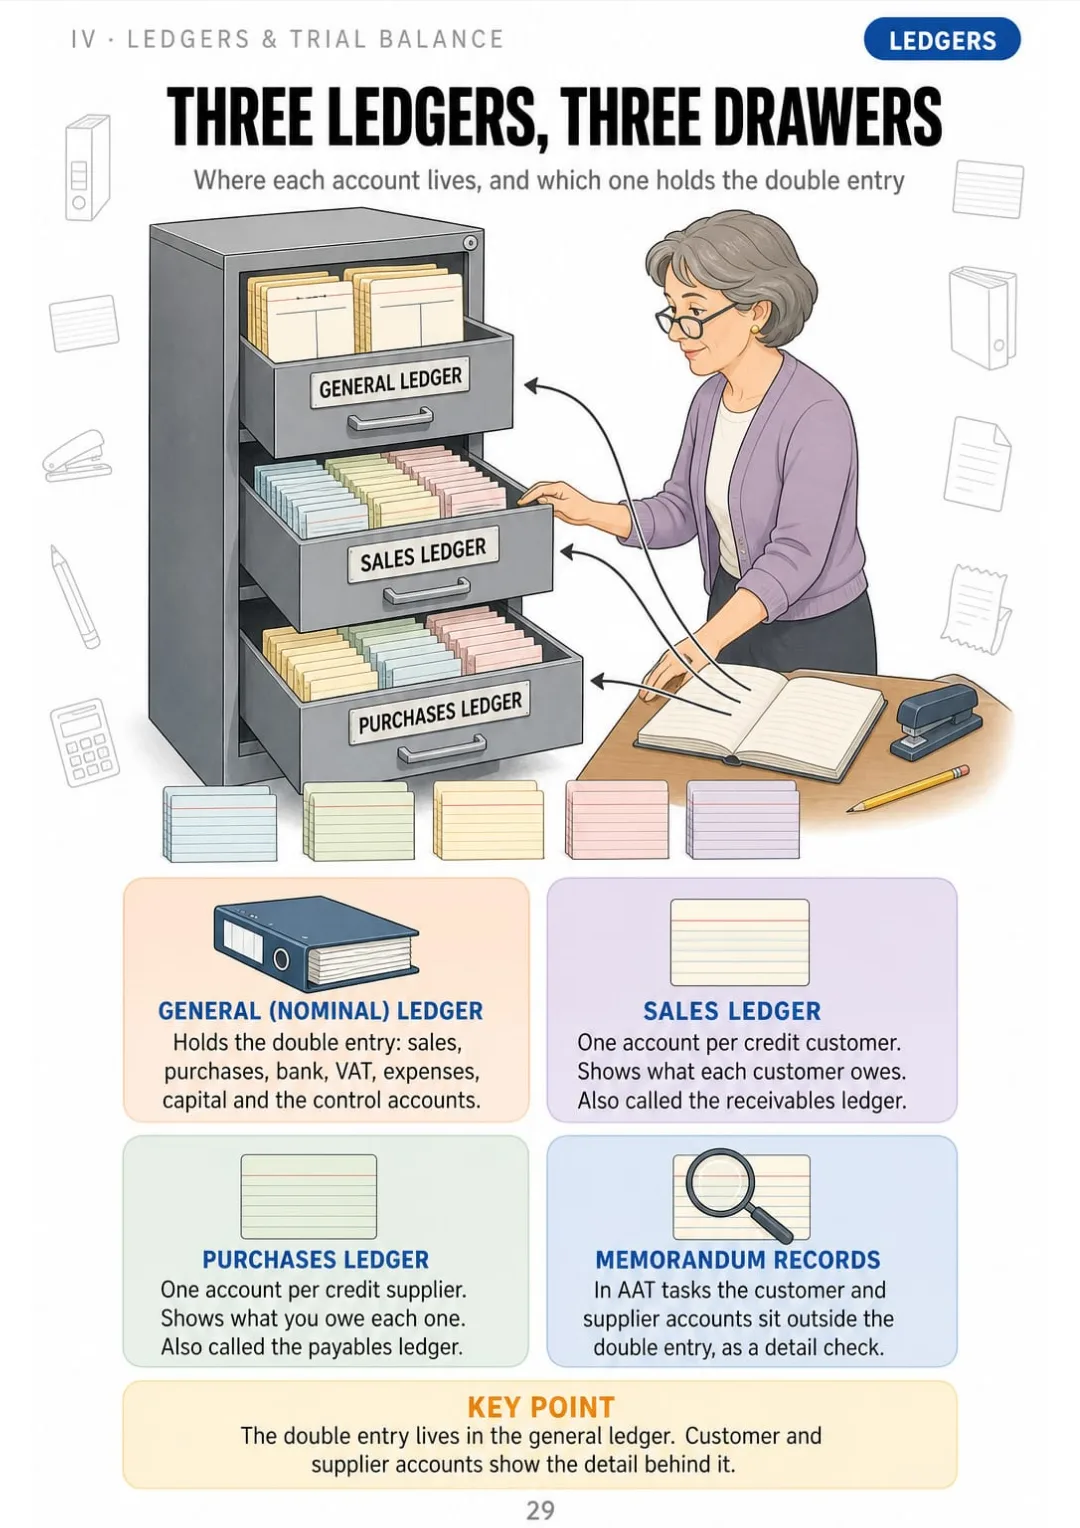
General ledger for the double entry; sales and purchases ledgers for one account per customer and supplier.
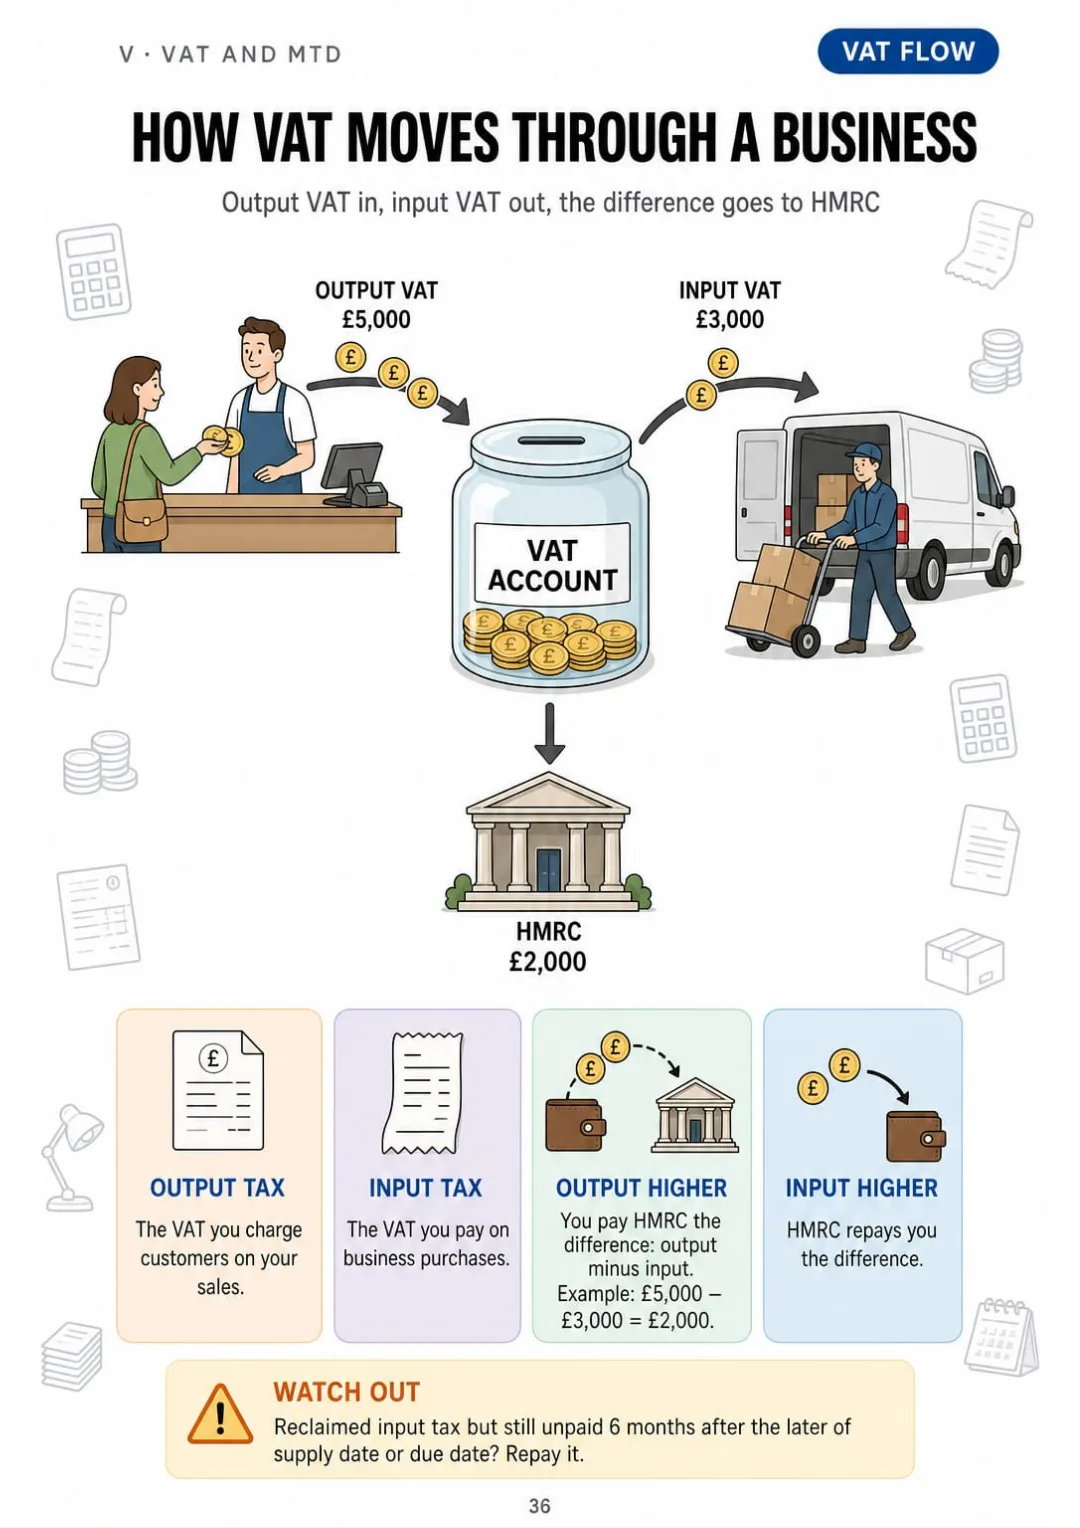
Output VAT minus input VAT: what you pay HMRC, or what HMRC repays you.
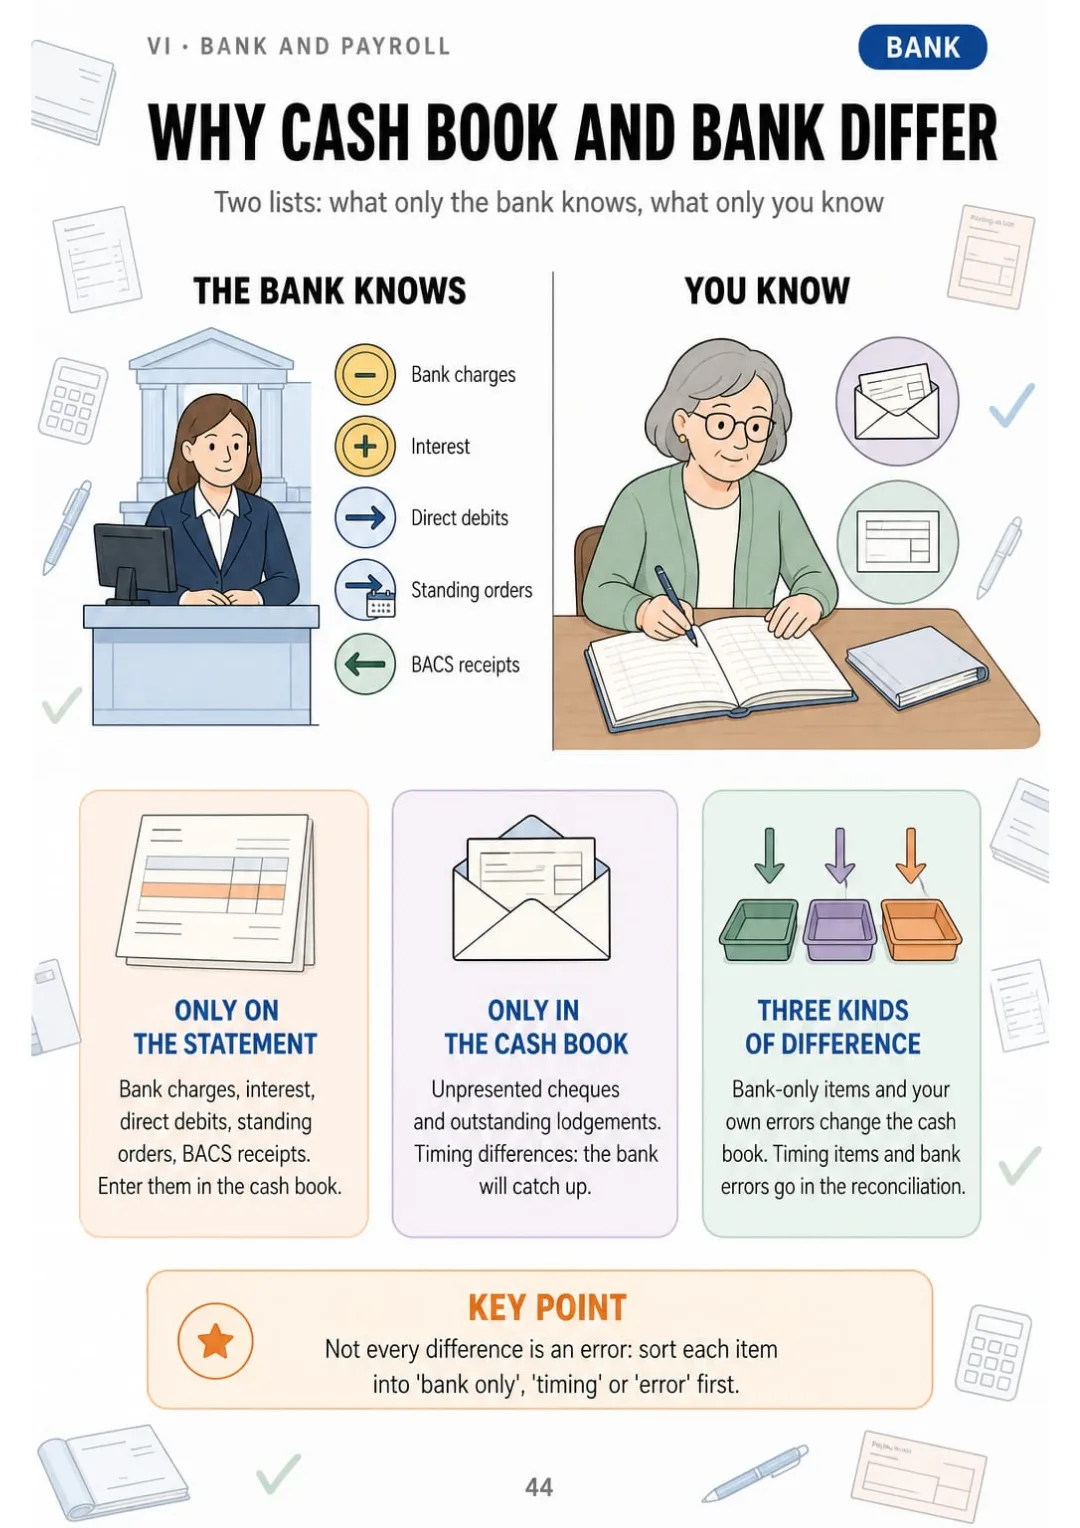
Charges, interest, direct debits vs unpresented cheques and outstanding lodgements
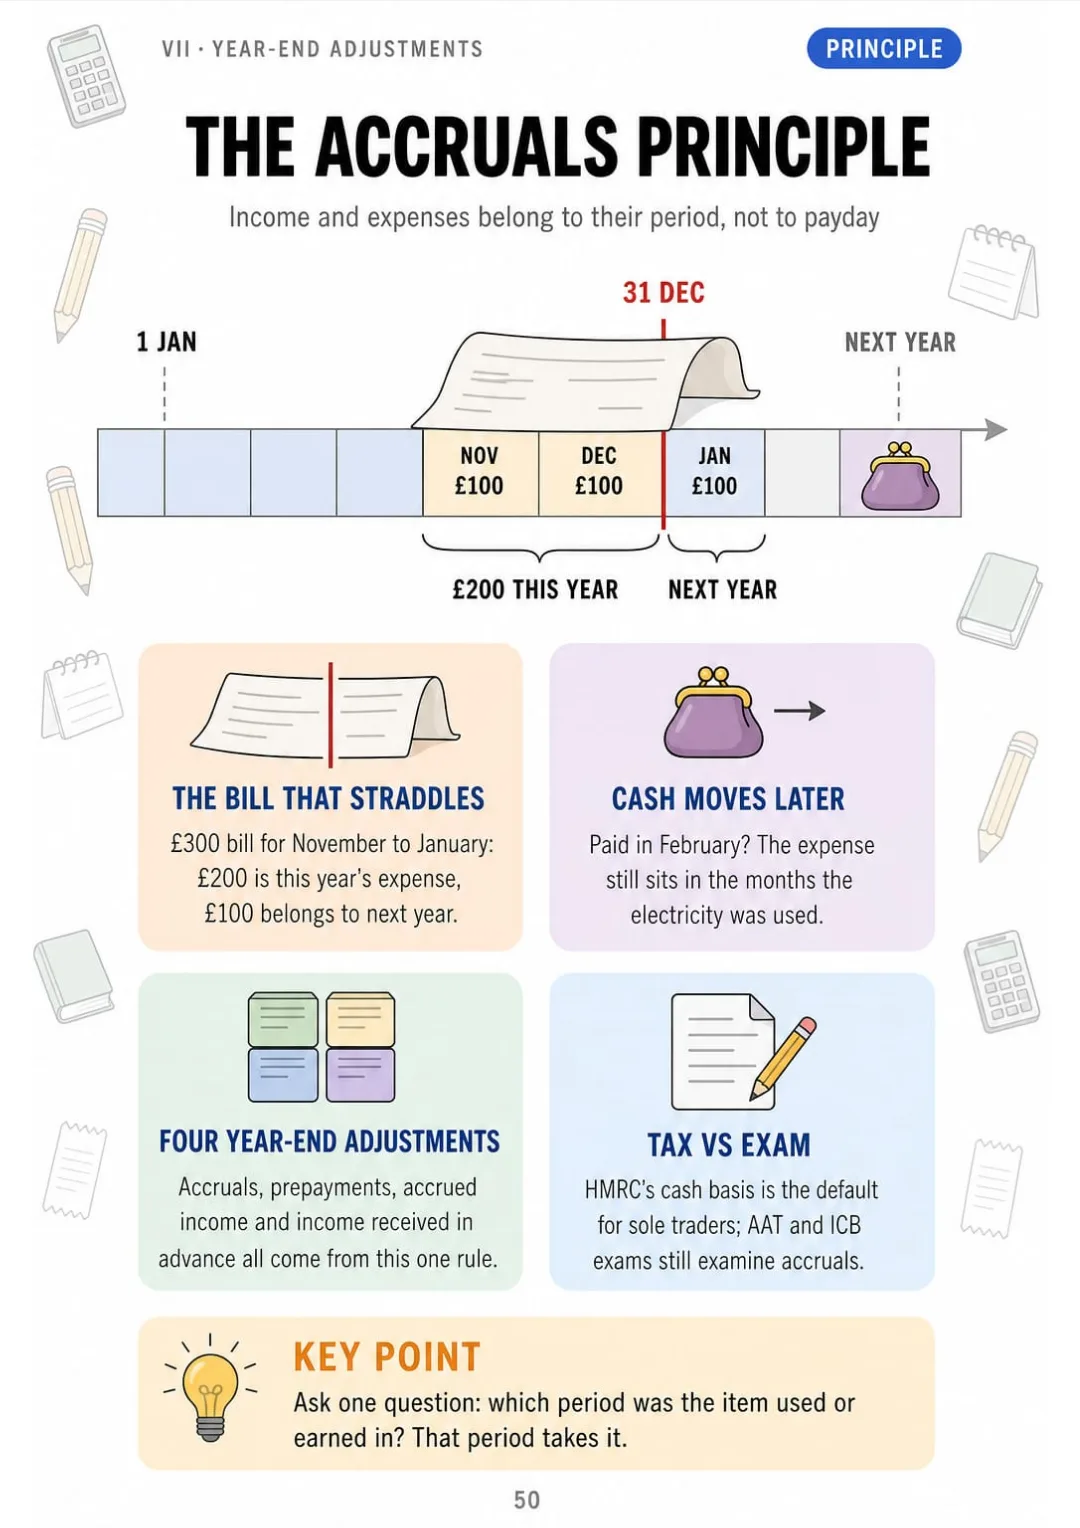
A £300 bill across the year end: £200 this year, £100 next year.
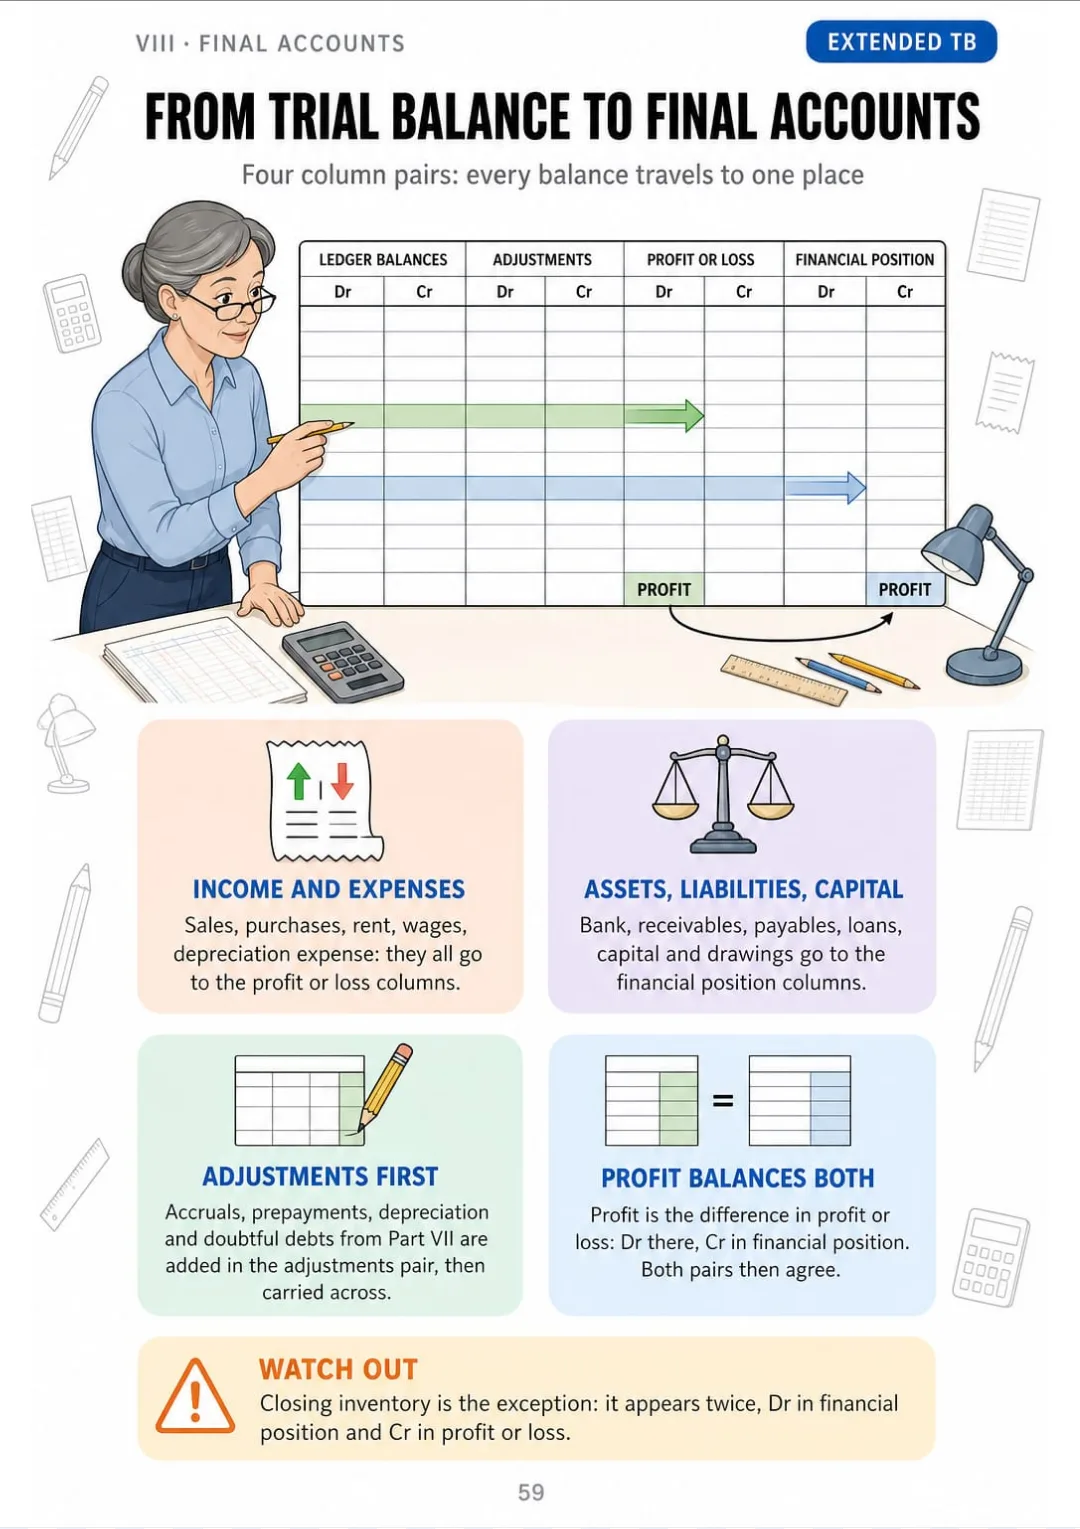
Extended trial balance: ledger, adjustments, profit or loss, financial position, each balance to one column

Take a Look at the 9 Parts and 65 Topics

The Big Picture

pp. 5-11
  1. The Route a Bookkeeper Always Follows
  2. Source Documents: Where Every Entry Starts
  3. Assets, Liabilities and Capital in One Drawing
  4. The Accounting Equation as a Scale
  5. Income and Expenses: What Moves the Scale
  6. Cash vs Credit Transactions
  7. UK Words You Will Meet: Old and New

Debit and Credit Without Memorising

pp. 12-20
  1. The T Account: Left Is Debit, Right Is Credit
  2. DEAD CLIC: The One Rule for Which Side
  3. Every Entry Has Two Sides
  4. Recording a Credit Sale
  5. Recording a Credit Purchase
  6. Returns: The Entry Runs Backwards
  7. Drawings: When the Owner Takes Money Out
  8. Capital Expenditure vs Revenue Expenditure
  9. Balancing Off a T Account

Books of Prime Entry

pp. 21-28
  1. Why Day Books Exist
  2. The Sales Day Book
  3. The Purchases Day Book
  4. The Returns Day Books
  5. The Cash Book: Day Book and Ledger at Once
  6. Discounts in the Cash Book
  7. Petty Cash and the Imprest System
  8. The Journal: For Everything Else

Ledgers and the Trial Balance

pp. 29-35
  1. General Ledger, Sales Ledger, Purchases Ledger
  2. Control Accounts: One Total for Many Customers
  3. Reconciling the Purchases Ledger Control Account
  4. Building the Trial Balance
  5. Errors the Trial Balance Shows
  6. Errors the Trial Balance Does Not Show
  7. The Suspense Account and Correcting Journals

VAT and Making Tax Digital

pp. 36-43
  1. How VAT Moves Through a Business
  2. The UK Rates: Standard, Reduced, Zero
  3. Net, VAT and Gross in Three Lines
  4. Posting VAT in the Ledger
  5. Registration: Threshold and Records
  6. The VAT Return, Box by Box
  7. VAT Schemes in One Page
  8. Making Tax Digital for VAT and Income Tax

The Bank and Payroll Basics

pp. 44-49
  1. Why the Cash Book and the Bank Never Match
  2. Bank Reconciliation in 5 Steps
  3. Overdrafts and Debit/Credit on the Statement
  4. Payroll Entries Without the Jargon
  5. Recurring Payments: Standing Orders and Direct Debits
  6. Keeping Records: What and How Long

Year-End Adjustments

pp. 50-58
  1. The Accruals Principle in One Drawing
  2. Accruals: Expenses Owed at Year End
  3. Prepayments: Paid in Advance
  4. Accrued and Prepaid Income
  5. Depreciation: Straight Line
  6. Depreciation: Reducing Balance
  7. Disposing of a Non-Current Asset
  8. Irrecoverable Debts and the Allowance for Doubtful Debts
  9. Closing Inventory

Final Accounts

pp. 59-63
  1. From Trial Balance to Final Accounts
  2. Cost of Sales and Gross Profit
  3. The Statement of Profit or Loss
  4. The Statement of Financial Position
  5. Sole Trader, Partnership, Limited Company: What Changes

Revision and Checklists

pp. 64-69
  1. DEAD CLIC Cheat Sheet
  2. Which Entry? 20 Transactions at a Glance
  3. Trial Balance Won't Balance: Search Checklist
  4. Bank Reconciliation and Control Account Checklists
  5. Year-End Checklist
  6. Frequent Mistakes Drawn Side by Side

Who This Book Is For

You're studying AAT or ICB

Each topic is one drawn page, so debit and credit, day books and ledgers follow one route you can see. You revise in the evening and it's still there in the morning.

Your exam is coming up

The checklists for the trial balance, the bank reconciliation and year end put the steps in the same order every time, and the workbook lets you practise with worked solutions.

You already keep the books

As a sole trader or the person doing the office accounts, you get VAT, the bank and year-end adjustments on one page each, ready to print and keep on the desk.

Plus: 2 Free Books

Bookkeeping Practice Workbook: Exam-Style Exercises with Worked Solutions
BONUS 1

Bookkeeping Practice Workbook: Exam-Style Exercises with Worked Solutions

Practise every topic with exam-style tasks, from T accounts to the trial balance, and check each answer against a worked solution, line by line.
The 10 Most Common Bookkeeping Mistakes: Before and After
BONUS 2

The 10 Most Common Bookkeeping Mistakes: Before and After

See the mistakes beginners make most often (wrong side, missed VAT, double posting) drawn side by side with the correct entry, so you spot them before they reach your trial balance.

30-Day Guarantee

30-day guarantee: if a file doesn't open, if the content isn't what the product page describes, if you were charged twice or the email never arrived, write to us and we'll refund you in full. You pay once. No subscriptions.

Frequently Asked Questions

Is it for me if I'm studying AAT or ICB, or doing my own books?

Yes. It starts from the route and the T account, so you can begin from scratch, and covers the bookkeeping in AAT Level 2 and ICB Level 2: day books, ledgers, control accounts, the trial balance, VAT and the bank reconciliation. Adjustments and final accounts help when you move on to Level 3. UK terms throughout, not American ones.

Where does the content come from?

UK bookkeeping practice and terminology as used in the AAT and ICB qualifications, in pounds and with UK terms. VAT rates, registration, the VAT return and Making Tax Digital are checked against HMRC guidance on GOV.UK, including VAT Notice 700. HMRC can change rates and thresholds, so GOV.UK is always the place to confirm the current figure.

Is it official material?

No. It's an independent illustrated study book. It isn't published, endorsed or approved by AAT, ICB or HMRC, and it doesn't give you a certificate or count towards your qualification.

Does it replace my course?

No. It's for studying and revising alongside your course, and it doesn't replace an accountant's advice for your own business.

Are the practice questions the ones from the exam?

No. The exercises in the workbook are written for this book, in an exam style, with worked solutions. They aren't official exam questions.

When and how does it arrive?

The book and the 2 bonus books arrive as PDFs by email, at the address you enter when you pay.

Do I have to pay every month?

No. It's a one-off payment, with no subscription.

Can I have it on paper?

Yes. The PDF is made to print, at home or at a print shop, in full or just the pages you need.

How does the refund work?

You have 30 days. We refund everything if the file won't open, if the book isn't what you see on this page, if you were charged twice or if the email doesn't arrive: just email us.

£19.99£57.99
Get the book · £19.99

This is a digital PDF book sent to your email: nothing is printed or shipped.